Finding the best state to retire on a fixed income has less to do with a top-10 list and more to do with your own monthly numbers. Here are the five costs that break a budget, and how to check each one before you move.
Find a Financial Planner Near You →Last updated: October 2026
What Is the Best State to Retire on a Fixed Income?
The best state to retire on a fixed income is the one where your monthly check covers your bills with room left over. That looks different for everyone, so no single list can name one winner for every reader.
Prices are a good place to start. The U.S. Bureau of Economic Analysis measures what it costs to live in each state compared with the national level.
In its 2024 data, the bureau found the lowest price levels in Arkansas, Mississippi, Iowa, and Oklahoma. The highest were in California, Hawaii, and New Jersey.
A low price level is only the start. Taxes, health care, moving costs, and the distance from your family can all break a budget that looked fine on paper. If the move also means a smaller home, our guide to downsizing for seniors covers that side of it.
The Five Budget Breakers
- Housing: rent and home prices swing more than anything else
- Taxes: income, property, and sales taxes all count
- Health care: supplement plan prices change with where you live
- The move itself: selling, packing, and getting there
- Distance: what living far from family can cost you
Where Can You Retire on $2,000 a Month?
The cheapest states to retire on a fixed income are the ones where everyday prices, especially housing, run well below the national level. That is where a $2,000 monthly budget goes the furthest.
For many people, $2,000 is close to what Social Security pays. The Social Security Administration reported an average retired-worker benefit of $2,087.52 in August 2026. Your own check could be higher or lower, depending on your work history and when you started benefits.
The bureau1 reports each state’s price level as a percentage of the national level. A number under 100 means prices are lower than the national level. This table shows the lowest and highest states in the 2024 data.
| State | 2024 Price Level | Compared With the National Level |
|---|---|---|
| Arkansas | 86.9 | About 13% lower |
| Mississippi | 87.0 | About 13% lower |
| Iowa | 87.8 | About 12% lower |
| Oklahoma | 87.8 | About 12% lower |
| New Jersey | 108.8 | About 9% higher |
| Hawaii | 110.0 | About 10% higher |
| California | 110.7 | About 11% higher |
The percentage differences are calculated from the bureau’s figures. These are statewide averages, and it also publishes figures for metro areas, so prices inside one state can differ from city to city.
Housing is the biggest swing. For housing rents, the bureau1 found California the highest at 154.3 and West Virginia the lowest at 54.2. A gap that wide can decide whether a fixed income feels comfortable or tight.
Do Income Taxes Decide the Best State for Retirees?
Income taxes matter, but they rarely settle the question on their own. Three kinds of taxes hit a fixed income, and most lists only talk about one.
As of 2026, Kiplinger lists eight states that tax Social Security benefits: Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont. Many of them exempt benefits below certain income levels, so some retirees in those states owe little or nothing on their checks. The rules differ by state and by income, and they can change.
At the other end, the Tax Foundation lists eight states with no individual income tax: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Wyoming, and New Hampshire. New Hampshire repealed its interest and dividends tax in 2025. Washington is often grouped with them, but it taxes capital gains.
A state with no income tax still has to raise money somewhere. Property taxes and sales taxes can run higher, and they hit a fixed income every month. Check all three before you decide, not just the income tax.
Tax rules change often, and your own mix of income decides what you would owe. A tax professional can run your real numbers against a state before you commit.
How Much Does Health Care Change From State to State?
What you pay for health coverage can change when you move, even if your Medicare stays the same. The biggest swing is usually the supplement plan.
Medicare.gov says Medigap premiums “vary widely depending on the insurance company, the plan, and where you live.” The price you pay today may not be the price in a new state.
Medicare Advantage plans work differently, because each one is tied to a service area. Under current rules, if you move outside your plan’s service area, Medicare.gov says your chance to switch plans begins when you move and continues for 2 full months after. It starts the month before if you tell your plan ahead of time.
Doctors matter just as much as premiums. Before you pick a state, find out whether the hospitals and specialists near you in that area take your plan. Not sure how the two plan types differ? Our guide to Medicare vs Medicare Advantage breaks it down, and a licensed health insurance broker can compare what is sold where you are moving.
What Does the Move Itself Cost?
Moving to a new state costs money before it saves any, and it comes out of the same fixed income. You may be paying for a mover, selling a home, and setting up a new place, sometimes all at once.
Quotes vary a lot by distance and by how much you bring, so get written estimates before you commit. Our guide to senior moving companies covers the questions to ask before you hire one.
If you are selling a home to pay for the move, the sale has its own costs and tax questions. A REALTOR® with the Seniors Real Estate Specialist® (SRES®) designation is trained to work with older homeowners, and a financial planner can help you see what the sale means for your monthly budget.
Many people shrink their belongings before they go. It lowers the moving bill and makes the new place easier to set up. Our downsizing tips for seniors show you where to start.
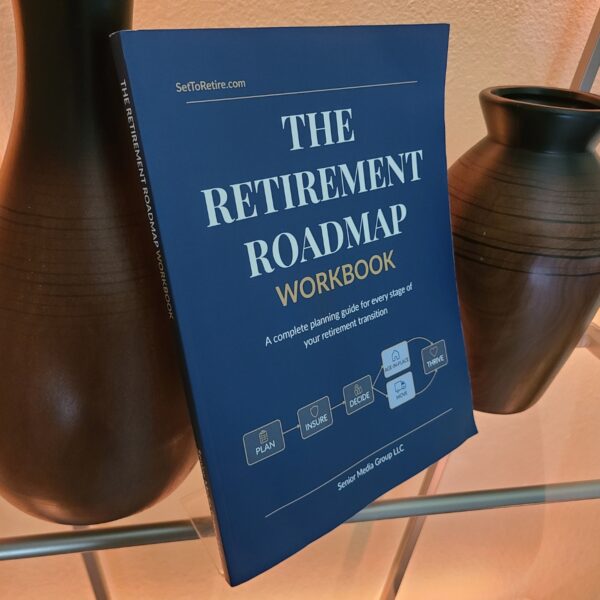
Weigh Staying Against Moving
The Retirement Roadmap Workbook’s Stay vs. Move Decision Matrix has you score factors like distance from family and nearby health care. Its financial comparison page puts the cost of staying next to the cost of moving.
See the Workbook → $47 · 138 pages · softcover
What Does Living Far From Family Cost?
A cheaper state gets expensive fast if it puts you a long way from the people who help you. Plane tickets, gas, and hotel stays add up for you and for your family.
If you ever need extra help at home, the people closest to you are often the ones who give it. Distance makes that harder and costlier for everyone. Our guide to long-distance caregiving shows what that looks like from your family’s side.
It is easy to pick a state from a top-10 list and run your real numbers later. By then a lease is signed or a house is listed, and changing course costs money. Run the numbers first, while every option is still open.
How Can You Test a State Before You Commit?
Spend real time in a state before you commit to it, ideally in more than one season. Many people rent in the new area for a while before they sell their home or buy a new one.
You see the real grocery bill, the real drive to a doctor, and how the weather feels once the visit is over. Use the five budget breakers above as a scorecard, and compare each one against your own monthly income.
Then picture the version where you chose well. Your check covers the bills, there is something left each month, and you can afford to visit the people who matter to you. That is what a fixed-income budget is for.
Frequently Asked Questions
Can you live on Social Security alone?
Some people do, especially where housing costs are low. Your own benefit depends on your work record and when you start it, so check your estimate by signing in to the online my Social Security account on SSA.gov before you plan around it. A financial planner can help you set that income against a state’s costs.
What are the best states to retire in financially?
There is no single answer, because “financially” depends on which costs matter most to you. Different lists weigh taxes, living costs, and health care differently, so their top picks change from list to list. Use the five budget breakers above as your own scorecard.
Do I have to tell Social Security if I move to another state?
Yes, you should update your address. The Social Security Administration says you can change your address for Social Security or Medicare benefits by signing in to the online my Social Security account on SSA.gov. If you get Supplemental Security Income, contact your local Social Security office instead.
Sources
You do not have to figure out a move like this alone. There are people in your area who work with these numbers every day, and asking one of them is a way to protect the income you worked for.
Free Download: Room-by-Room Downsizing Checklist
Planning a move to a smaller place? Enter your email and we’ll send you this checklist so you can sort what comes with you and what doesn’t.
Continue Reading: Downsizing & Moving Guides
Content on SetToRetire.com is researched and drafted with AI assistance, then reviewed and edited for accuracy by the editorial team at Senior Media Group LLC. It is provided for general informational purposes only and does not constitute financial or tax advice. Consult a qualified financial or tax professional before making decisions. For more on how we create content, see our Editorial Process.